Your house suffered heavy damage during a storm in your area. The insurance company adjuster showed up and you worked with him to file a claim. To your delight, the insurance company agreed with the adjuster and processed the claim speedily. You got the check, but when you opened the envelope and looked at it, the amount was less than the claim. On the attached explanations, you see that the difference is listed as recoverable depreciation.
What is recoverable depreciation? Recoverable depreciation is the difference between the replacement cost of the damaged property and its actual cash value. If your insurance policy is for replacement cost, the insurance company will pay you this difference when the repairs are completed and you send proof.
Insurance claims can get complicated and involved. Understanding what goes into an insurance claim, the terminology and language of the insurance industry, and how the calculations that lead up to your eventual settlement are made is critical. Before you purchase your homeowner's insurance policy, you should consider how these things might affect you in the event of a calamitous loss.
The Key Difference
Many people are under the impression that homeowner’s insurance will replace or repair any loss that they suffer. Unfortunately, this isn’t always true. How much you can recover from your insurance coverage after a loss depends on how the homeowner's insurance policy was written and the options you elected to add to the policy at the time you agreed to the contract.
Let’s look at what you can expect from a standard actual cash value homeowner's policy in the event the home is damaged.
The Claim – You filled out all the paperwork, and the adjuster looked at your loss and calculated his estimate of what your claim is worth. You agreed, and the claim was filed. In our example, let's say the adjuster estimated that the loss to your home was $10,000.
- What you can expect to get – When you get your settlement check, it will be made out for less than the actual claim. Here’s why
- Depreciation - Everything has a life expectancy, even your home. Our claim on our damaged roof is calculated on the age, condition and life expectancy of the roof. Let’s say the adjuster decides our ten-year-old roof has lost 40% of its value. Our claim would be reduced by that 40% to $6,000, which is the actual cash value of the roof. How insurers may calculate depreciation, including whether they may depreciate the labor in a repair as well as the materials, varies by state.
- The deductible – Your insurance policy has a deductible. This is the amount that you are responsible for paying as part of the contract. Let’s assume your insurance policy has a $1,000 deductible. The amount that the insurance company pays you is reduced by that $1,000. Your settlement check is reduced by that $1,000 dollars as well to $5,000.
- The Final Payment – This $5,000 constitutes the final and full payment that we will receive on our $10,000 dollar loss. If the roofing company replaces the roof for $10,000, as was estimated, the difference must be made up of our personal money.
Seeing those kinds of numbers can be shocking. Most people think that insurance on their home is going to repair, replace, or rebuild their homes. Unfortunately, a homeowner's insurance policy that has only actual cash value coverage can leave the homeowner with a large bill in the case of a major loss, and the older the damaged property, the larger it gets. This is where recoverable depreciation is key.
Figuring Recoverable Depreciation into the Picture
If the homeowner's policy had a replacement cost add-on with the policy, the scenario changes drastically. Taking the same set of circumstances and the same $10,000 claim against an insurance policy that pays replacement costs, allows us to capture that depreciation, which is now termed recoverable depreciation.
- After the Initial Claim Payment – We should receive our claim check from the insurance company for the $5,000. However, since we have a replacement cost homeowner's insurance policy, we can expect to get additional payments from the insurance company when the work is finished.
- Interim Payments – If the expected recoverable depreciation is large, the insurance company may agree to pay out that amount in smaller settlements as the work progresses. On most smaller claims, the recoverable depreciation is paid when the work is finished. In our example, when the roof work is completed and we send the insurer the final invoice, we will receive a check for $4,000 dollars.
- Deadlines – Most replacement cost policies set a time limit for completing the repairs and claiming the depreciation, and some states extend that limit by law. Check your policy, and if the repairs will take longer, ask the insurer in writing for more time before the deadline passes.
This makes a huge difference. Instead of having to foot $5,000 of the cost to replace our $10,000 roof, with recoverable depreciation, we are only responsible for the $1,000 deductible. You can see how having a homeowner's policy with replacement value coverage can be a lifesaver.
Disadvantages and Advantages
There are advantages and disadvantages to both kinds of homeowners' insurance policies. You should consider your options, consult with a professional financial advisor or your insurance agent, and get their advice before deciding. Some things to consider as you explore your options are:
- Actual cash value coverage usually costs less in premiums, but you carry the cost of depreciation yourself when you have a loss.
- Market value and insurance value are different things. Your policy insures the cost to repair or rebuild your house, not what it would sell for, and not the land under it, so a rise or fall in your home's market value does not change what a claim pays.
- Insuring your home at replacement value protects you financially from depreciation, though you still pay your deductible, your payment is still capped by your policy limits, and you generally collect the depreciation only if you actually repair or replace the damaged property.
- Replacement cost estimates vary over time. You should re-evaluate the replacement cost that is written into your homeowner's insurance policy each year at renewal time.
Whichever type of homeowner’s policy you elect to purchase, it is your responsibility to know and understand the contents of that policy. The insurance policy is a contract between you and the insurance company. As with any contract, you should read and understand the provisions of the contract. Knowing the limits of your coverage, the values that are set on your home and its contents, and the way the insurance company will handle any claims is vital to protecting your interests.
Why is my Mortgage Company on my Claims Check?
Your lender has a vested security interest in your house. They, in effect, are your partner in your home purchase until you pay back the money they loaned you to purchase the house plus any interest that is owed. It is in their interest to see that the insurance settlement is used for the purposes of rebuilding or repairing the damage to the home to maintain its value. Several things can happen at this point.
- The lender may instruct you to endorse the check and send it to their office. The lender has several options at this point.
- The lender may endorse the check and send it back. This is often the case on small claims.
- Payments for personal property, such as clothing or furniture, are often made out to you alone, because the lender's interest is in the house. If a check combines both, ask the insurer whether it can issue the personal property payment separately.
- Larger claims or the portion of the claim for repair or replacement of your home will probably be held by the mortgage company and paid out in smaller checks as work is performed. In some instances, the lender may send the checks directly to the contractor performing the work once they are satisfied the work is completed satisfactorily. Each lender has its own process, so call its loss draft department early to find out what it needs.
What is Additional Living Expense?
If your home is badly damaged and you cannot live in it while it is undergoing repairs, your insurance policy may pay for certain expenses that you incur while you can’t live in your home. Some of these additional living expenses are:
- Rent or hotel fees
- Pet Boarding if your temporary lodging won’t accept your pets.
- Gas and Mileage if you must travel further to work than normal.
- Food if your temporary lodging has no cooking facilities, and you must eat out consistently.
Some insurance policies contain provisions for advance additional living expenses. These quick sums of money allow you to plan for you and your family without stressing your personal finance.
There are some critical things to know about additional living expenses.
- ALE reimbursements are usually capped. Your policy probably sets a maximum amount the insurance company will pay toward ALE.
- Some policies set a time limit for ALE reimbursements. Claims for ALE must be submitted within this time frame to be considered.
- Ask the adjuster to tell you in writing which expenses are reimbursable under your policy, since the policy itself rarely lists them. Keep receipts for everything.
Don’t get confused about what constitutes ALE and what should be covered under the personal property provisions of your insurance policy. If you are displaced from your home, there will be lots of needs as an example.
- Having to move into a hotel or rent an apartment to live in is covered under the ALE provisions of your insurance policy and should be claimed as such.
- If you and your family lost all your clothing and need to purchase new clothing, these expenses should be claimed as a personal property loss and filed under that portion of the policy.
My Contractor Started Repairs and Found Additional Damage. What Do I Do?
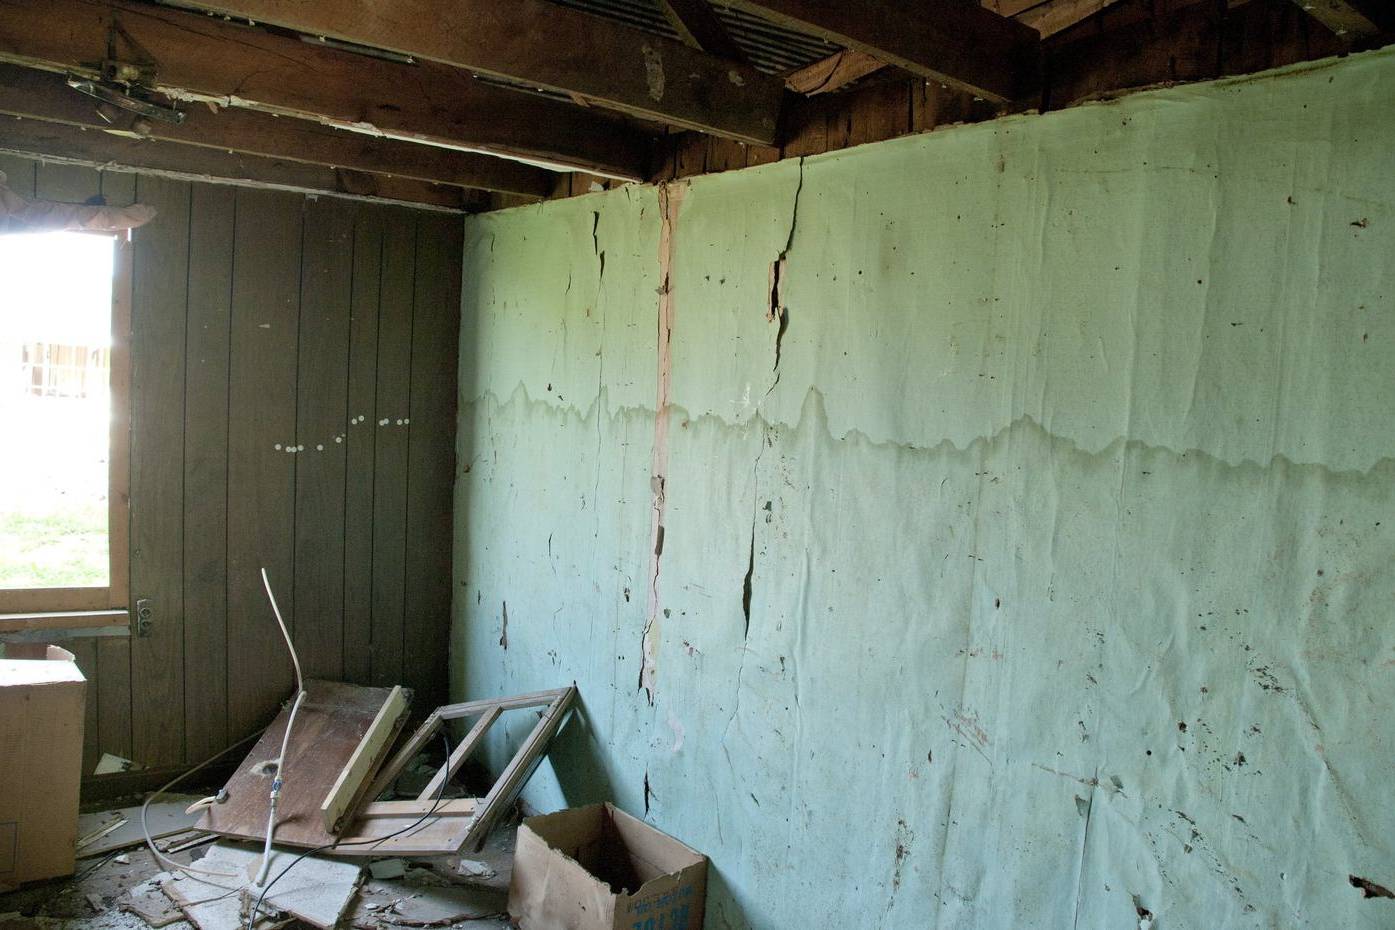
All too often, insurance adjustors miss or can’t see all the damage that needs to be addressed. This is particularly true where damage to a home is severe, and the adjuster can’t see portions of the structure still covered by the finishes. When the contractor begins demolition before the rebuilding or repairing process, it is common to find structural damage that must be addressed.
You will need to file a supplemental claim in this case. Your contractor can document and price the additional damage, though in many states only you, an attorney or a licensed public adjuster may negotiate the claim with your insurer. These are the steps to follow.
- Notify the insurance company before the additional damage is repaired or covered up, so it has the chance to inspect it.
- Contact the original adjuster or your insurance agent to get the exact steps you should follow to file the supplemental claim.
- Generally, the supplemental claim will be sent to a company adjuster for approval. The insurance company has the right to do a follow-up inspection.
- Document your supplemental claim with pictures, videos, and further estimates of the additional work and materials that will be required.
Disclaimer
This article does not constitute legal advice and is intended for educational and informational purposes only. Before entering any contract, you should consult an attorney for legal advice.
The Bottom Line
In the end, the goal of buying homeowners' insurance is to accomplish several things.
- To protect you and your family against the loss of your home and personal belongings.
- To protect your financial security.
- In the case of a loss, to return your home and family to the same as it was before the loss occurred.
Whether you choose actual cash value or replacement value homeowners, insurance coverage is a decision you must make based on your evaluation of the best set of options. You should do your due diligence in making that decision by consulting your insurance agent or a public insurance adjuster and educating yourself about the options available in the homeowner's insurance market. If you already have a claim and are unsure whether your depreciation was calculated fairly, Melo Property Claims can review it in the states where we are licensed.
I hope that this article has helped you understand a bit more about how actual cash value and replacement value can affect you in the event of a loss. Recoverable depreciation is certainly a large factor in making decisions about what kind of homeowner’s insurance coverage to purchase.
It is our aim to give you a clearer understanding of how these things work and how they can affect you if you must file a claim with your homeowner's insurance company.