Builders Risk Insurance, often referred to as Course of Construction Insurance or simply Builders Insurance, is a vital component in the construction industry. It provides coverage for property and materials at a construction site. However, the question of who pays for Builders Risk Insurance can vary depending on the circumstances and the parties involved in a construction project.
Builders Risk Insurance policy
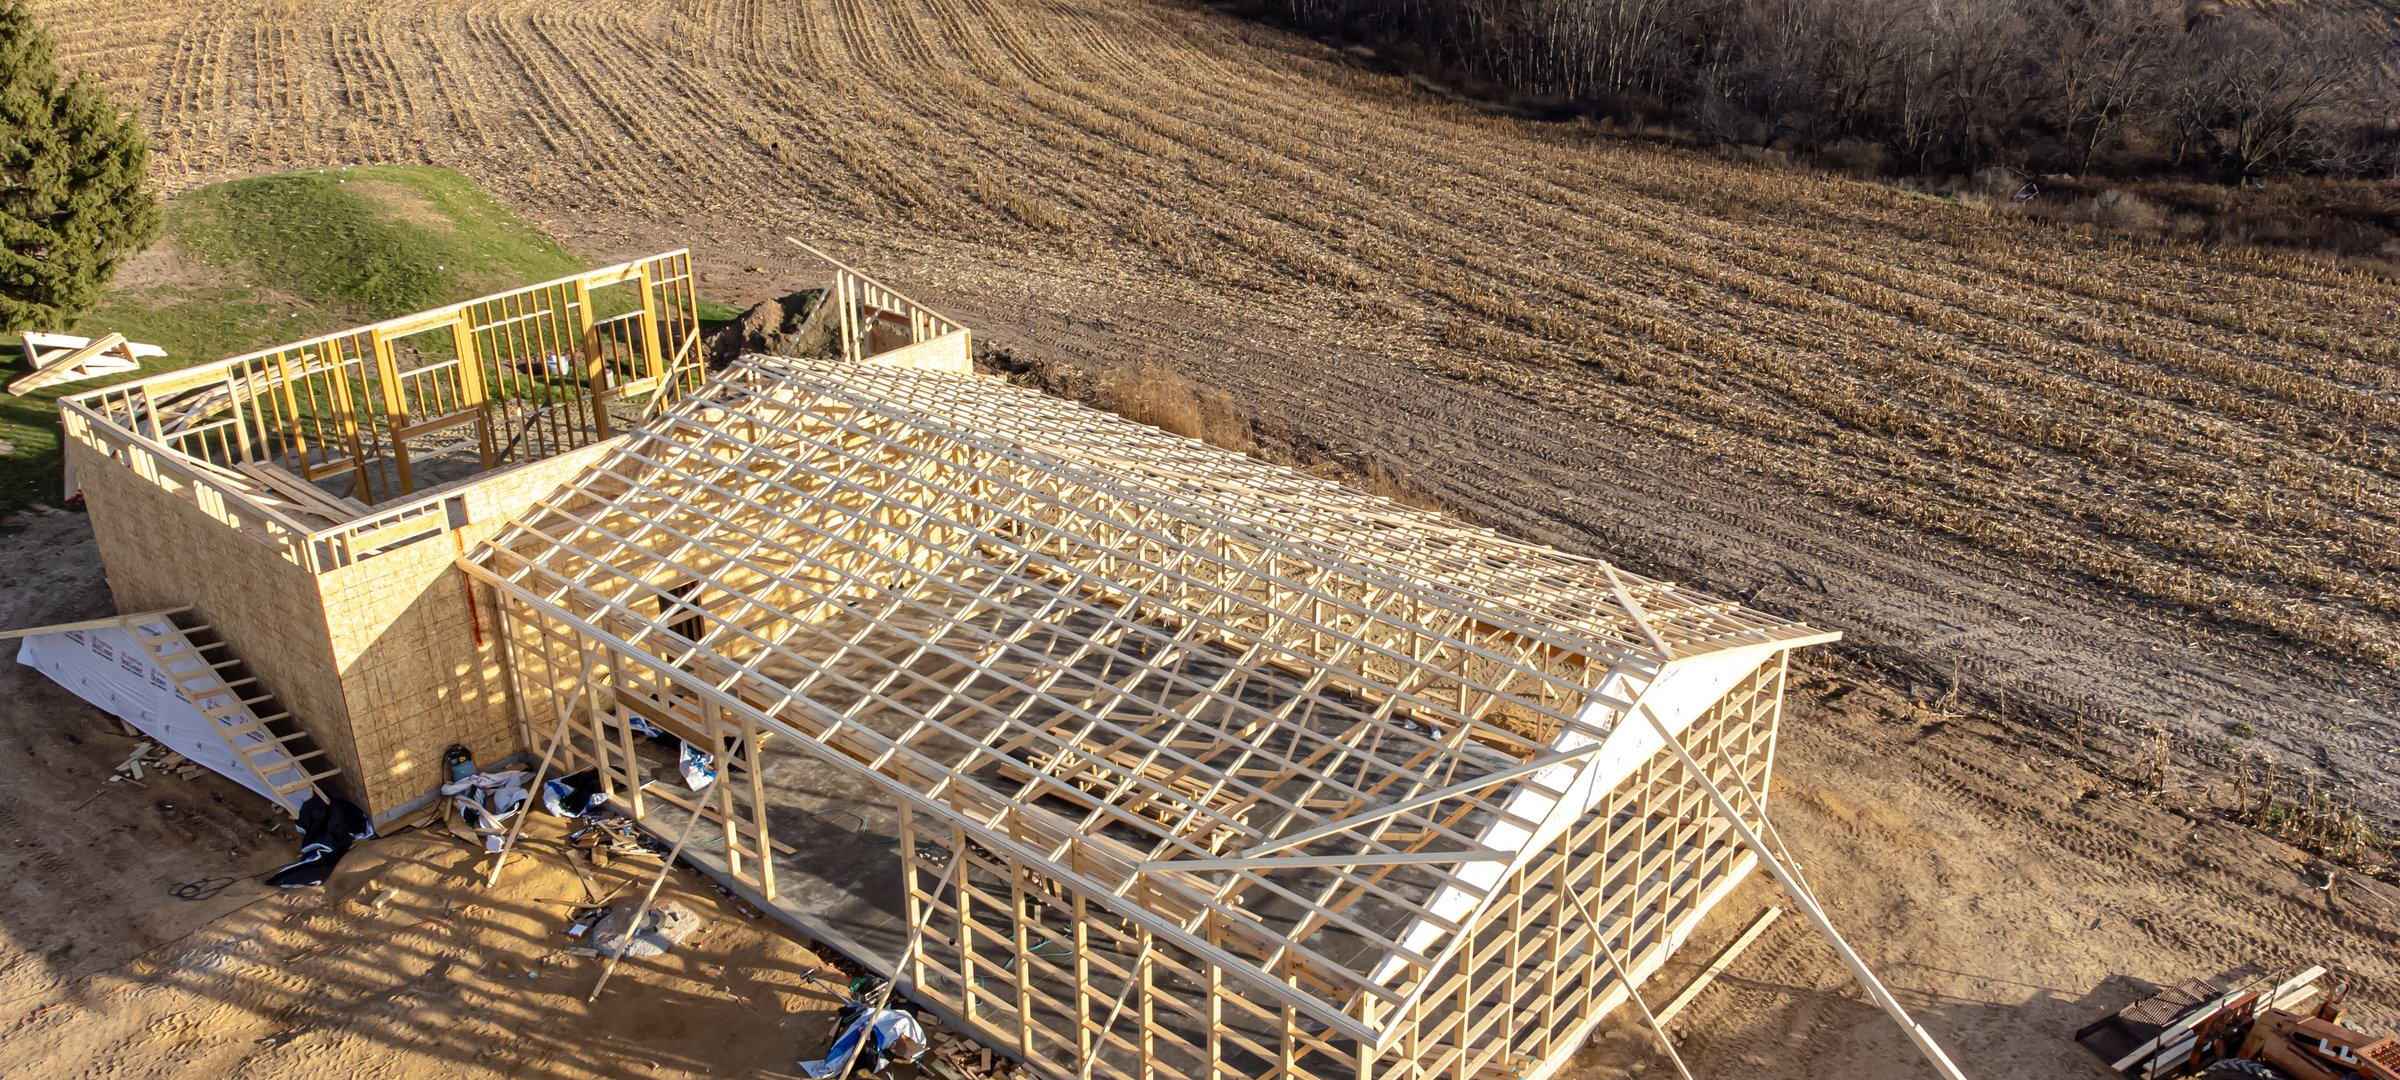
Builders Risk Insurance policies are designed to protect against losses or damages to a construction project's property and materials while the work is in progress. These policies typically cover risks like fire, theft, vandalism, and certain weather-related events. Flood and earthquake are often excluded or limited unless added, so check the policy for the risks your site faces. They can be tailored to the specific needs of a construction project, whether it's a new build, renovation, or an addition to an existing structure.
Who buys the Builders Risk Insurance policy is usually decided by the construction contract, and it is most often either the project owner or the general contractor. When the owner buys it, the owner pays the premium directly. That makes sense because the property owner has a vested interest in protecting their investment and ensuring that the project progresses without significant financial setbacks. Whoever buys it, the other parties with an interest in the project, such as the contractor and the lender, are often added to the policy.
On many projects, especially new homes built by a builder, the owner instead requires the contractor or builder to buy the policy and include its cost in the bid. This means that while the property owner ultimately pays for the coverage, they do so indirectly by incorporating it into the overall project budget. This approach ensures that the cost of insurance is factored into the project's expenses from the outset.
However, it's crucial to note that the responsibility for Builders Risk Insurance depends on the terms of the construction contract, so read it before work starts. Policies can also be written in different ways. Some insure the project's full completed value from the start; others, often called reporting forms, cover the value as it grows, with the insured reporting the value of the work as it progresses. On a phased project, make sure each phase is insured by someone and that there is no gap between one policy and the next.
In the context of renovations, Builders Risk Insurance for renovations is tailored to the risks of altering an existing structure. Whether it also covers the existing building, and not just the new work, depends on the policy: some include it, many cover it only if it is added, and otherwise the existing building stays under the owner's property policy. Tell your property insurer about the renovation too, since some policies restrict coverage while a building is vacant or under construction.
In conclusion, the party responsible for paying for Builders Risk Insurance depends on the terms of the construction contract. The property owner either buys the policy or pays for it through the contractor's price, and on renovations the existing building may need its own arrangement. Regardless of who pays for it, Builders Risk Insurance is a critical safeguard against damage to the property and materials while the work is under way. If you have a builders risk loss and the claim stalls, a licensed public adjuster who handles builders risk claims can help; Melo Property Claims works across the states we serve.