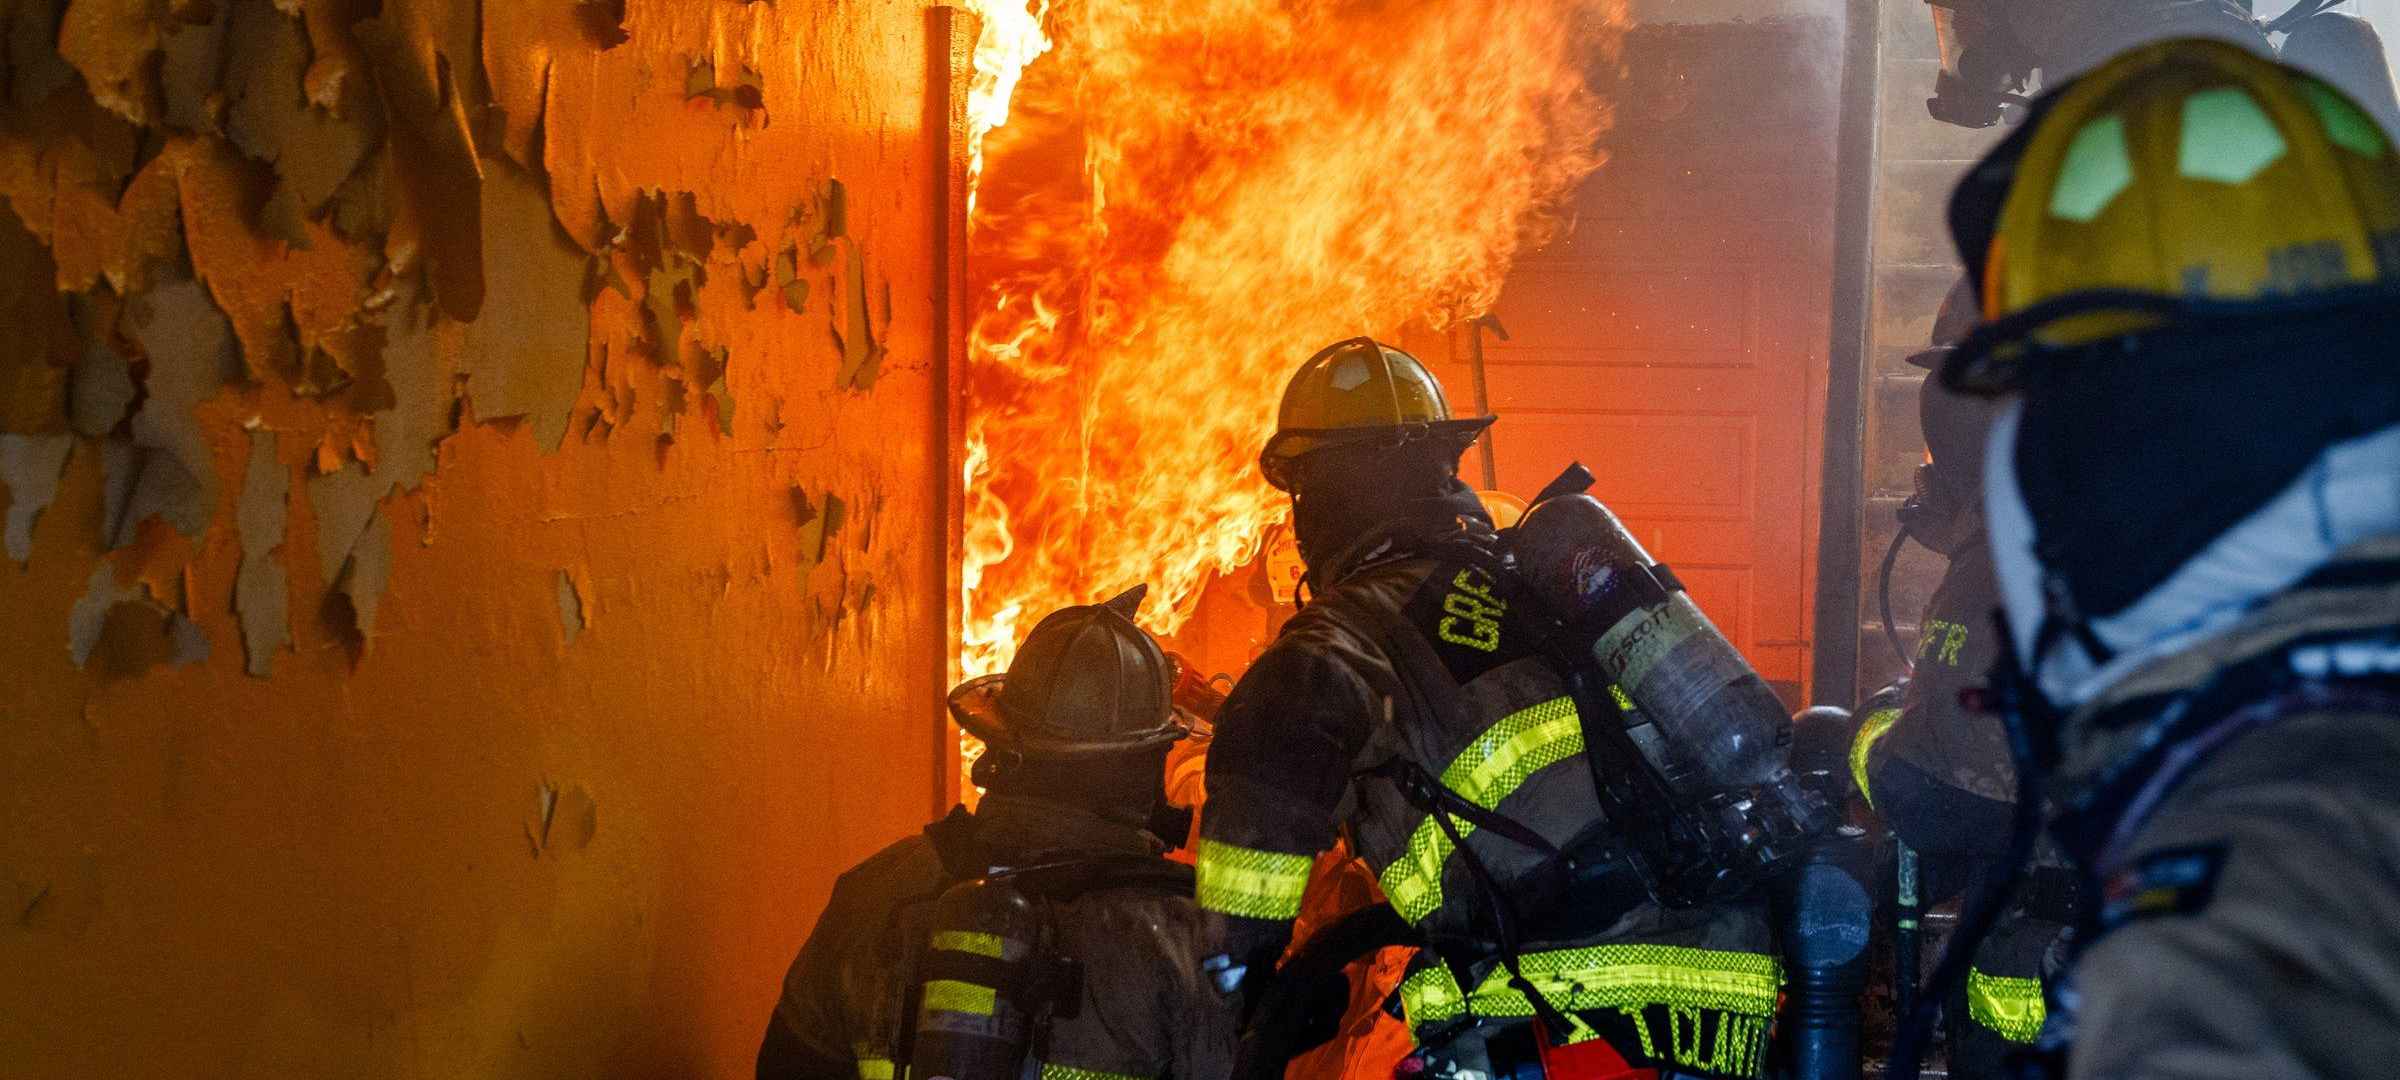
Knowing how to deal with an insurance adjuster after a house fire can make the entire process less stressful for a homeowner, and help ensure you are paid everything your policy owes. The adjuster your insurer sends works for the insurance company. A public adjuster works for you, the policyholder, and negotiates with the insurance company on your behalf, but relies on you for accurate, detailed information about your claim.
Understanding a little bit about public adjusters, including when to hire one and how they manage the procedure of negotiating with insurers, can also make it easier to work with them. To prepare you for your initial phone call and everything that follows, consider some quick yet comprehensive tips for how to deal with an insurance adjuster after a house fire.
What Is an Insurance Adjuster and When Should You Hire One?
First note that a public insurance adjuster works for you, the policyholder, to negotiate with the insurer and recover everything the policy owes without having to take the insurer to court. A public adjuster typically gets paid a percentage of the settlement; the percentage is set in your contract, and some states limit what a public adjuster may charge, so the rules depend on where the property is. See what a public adjuster charges.
Because a public adjuster gets paid a percentage of the settlement, their interest lines up with yours. You also don’t usually pay them out of your pocket before work begins.
It’s recommended you hire such an adjuster if you feel your insurance company is not offering a fair settlement or if you’re struggling to file the claim properly. A house fire claim is often difficult to file properly and completely, as you might need to itemize a number of personal items and other expenses incurred after the fire, such as cleanup and odor neutralizing.
What to Do Immediately After you Experience a House Fire
The first thing to do after a house fire is filing a claim with your insurer; even if you know immediately that you’ll be hiring a public adjuster, most insurance companies require notification or filing of a claim “as soon as reasonably possible.” Once you and your family are safe, at least call your insurer’s claims line or your agent to report the fire and ask about the next step to the filing, if you’re not sure how to go about it.
Also, most insurers require their policyholder to do everything reasonably possible to “mitigate damage,” meaning keep that damage from getting worse. After a house fire, avoiding added damage might mean boarding up windows to keep out rain or snow as well as potential thieves, removing personal items so they don’t absorb residual water used by firefighters, and the like.
Additional Steps to Take After a House Fire
- A homeowner would also do well to start itemizing all personal items damaged beyond repair, and especially before you start boxing up items or throwing anything away! This includes kitchen appliances, furniture, electronics, clothing, and so on.
- Note as many details as possible on this list, including an item’s age, size (such as for kitchen appliances, mattresses, etc.), approximate value, manufacturer, and place of purchase. Use a spreadsheet to make this record easier and keep things organized! Take photos of the home’s damage overall as well as photos of individual items.
- You might also find as many receipts for damaged items as possible; if you don’t have paper receipts, check your bank statements, as these should still have a record of items you purchased with a credit or debit card. Obviously, you won’t be able to remember every detail for everything you’ve lost in the fire; however, the more information and photos you can provide, the easier it will be for your public adjuster to research your claim and negotiate with your insurer.
How to Deal With an Insurance Adjuster After a House Fire
Now that you’ve done your due diligence to protect your property after a house fire, it may be time to call a public adjuster. You choose your own; you’re not obligated to use anyone your insurer suggests. Look for one licensed in your state (check with your state’s insurance department), with good references and experience with fire claims.
- A public adjuster will want to review your homeowner’s insurance policy, so have that ready for them as well as your claim number and the contact details of your agent and the insurer’s adjuster.
- Adjusters typically investigate claims on their own, so they’ll also want copies of the fire department’s report and any police reports.
- Your adjuster will also want to tour your damaged home; don’t be offended if they go through every room and space, as they know that heat and smoke damage more than just the room where the fire occurred.
- A public adjuster will often inspect items you’re listing on your claim, including damaged appliances and furniture.
- A public adjuster will also need to note additional expenses you’ve incurred with a house fire beyond actual losses, such as water damage cleanup services or a hotel bill.
What Do Claims Adjusters Look For?
A public adjuster needs to know everything possible about your house fire and its resultant damage if they’re going to negotiate properly with your insurer. As they tour your home, they will note the extent of damage as well as needed cleanup, such as smoke stains on the ceiling, water trapped in carpeting, and other issues homeowners often overlook.
Public adjusters also understand long-term costs associated with house fires, and which homeowners might forget to include on their claim. For example, a home might need mold remediation, to protect it from mold that often results from the copious amounts of water used to extinguish a fire! Odor neutralizing services remove bothersome smells that tend to linger long after a fire is addressed.
Homeowners also might not realize that many expenses incurred because of the fire may be covered under their insurance policy. For example, if you’ve had smoke-damaged clothes dry cleaned, that cleaning bill might be included in your claim. Keep track of any expense you’ve incurred due to the fire even after hiring a public adjuster, including cleaning bills, tabs from restaurants you’ve had to visit because your kitchen is unusable, a moving service that helped box up and remove undamaged items in the way of your water repair company, and the like.
How Do You Negotiate With an Insurance Adjuster?
A policyholder doesn’t negotiate with their own public adjuster, as he or she works for you and gets paid a percentage of what they secure from your insurer, as said. You might, however, consider some tips on how to make their job easier when it comes to negotiating with your insurer!
One common point of contention between policyholders and insurers is a claim for items that can be cleaned and repaired versus those that need disposal. Don’t get overeager when it comes to your list of items needing replacement, perhaps assuming that your policy will reimburse you for anything and everything in the home touched by the fire.
In the same way, use caution about restoration companies that approach you after a fire, and ensure you work closely with any water or fire damage cleanup contractor you do hire. He or she might try to pressure you to sign off on unnecessary cleaning and repairs, only for you to find out that the work is not covered by your insurance policy.
To ensure smooth negotiations with your insurance company, communicate very closely with your public adjuster about any such expense or work you’re considering. While he or she can’t make decisions for you, they will know your policy well, so they can offer cautions about claiming certain items and keep you from common mistakes that make negotiations more difficult overall.
What Happens If You Reject a Settlement Offer?
If your public adjuster returns from negotiating with the insurer with what you feel is a lowball offer, or one that doesn’t cover everything lost in a fire, remember that he or she gets paid a percentage of what they secure, so their interest is the same as yours. Before you assume you made a wrong choice in hiring them, discuss your options.
As an example, your adjuster might explain that your losses actually exceed your policy limits, which is more likely if you haven’t reviewed your coverage in many years. If building costs have risen or you bought new furniture, appliances and other belongings without raising your limits, your losses might exceed what the policy will pay. Jewelry, art and other valuables are often capped at low limits unless they were scheduled on the policy.
If your policy does offer more coverage than the settlement you’ve been offered, there may still be options. If the dispute is only about the amount of the loss, your policy’s appraisal clause may apply, and some states offer mediation programs; your adjuster can explain what is available. If those don't resolve it, you might need to take your insurance company to court. Note that a public adjuster is not an attorney and cannot offer legal advice. Be prepared to hire a separate attorney for a lawsuit, which usually means more time before you are paid, and watch the policy’s and your state’s deadlines for filing suit.
Related Questions
Should you always hire a public adjuster after a house fire?
If you believe your insurance company has acted in good faith and that you’ve received a fair compensation offer for expenses and losses after a house fire, you probably don’t need to hire a public adjuster. This is especially true if the fire was small and losses minimal.
How long does it take for a public adjuster to secure a settlement after a house fire?
There is no “one size fits all” answer as to how long a public adjuster takes to secure a settlement after a house fire. They need to document the loss and build the estimate, and then the insurer has to respond. A small, straightforward claim can settle much sooner than a total loss or a disputed one. Many states set time limits for insurers to acknowledge, decide and pay claims; your state’s insurance department can tell you what applies.
This information is presented by Melo Property Claims. If you still have questions about how to deal with an insurance adjuster after a house fire or need a public adjuster to negotiate with your insurance company for you, our licensed public adjusters handle fire claims for homes and businesses in each of the states we serve. Call Melo Property Claims today.